Personal finance advice usually breaks down at the same point: it assumes you have spare money lying around. Most people don’t. They have a salary that arrives on the first, a rent due on the fifth, a parent’s medical bill nobody planned for, and a vague feeling that they should be doing more.
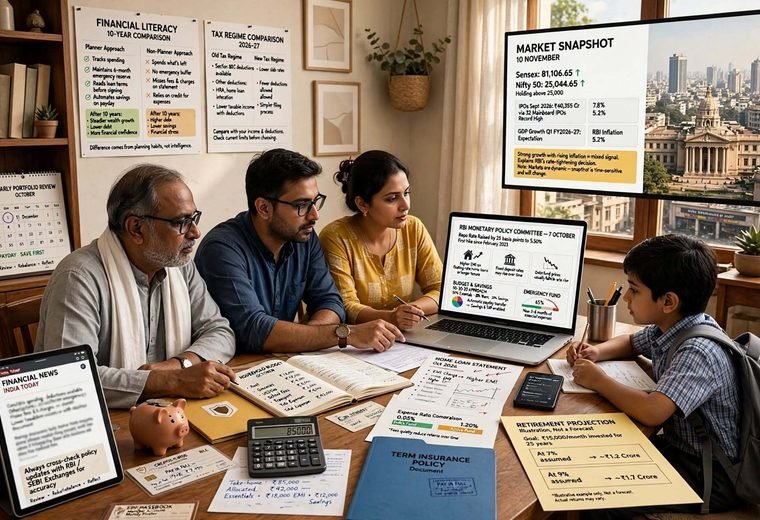
This year, the stakes feel a little higher. On 7 October the RBI raised the repo rate by 25 basis points to 5.50%, its first hike since February 2023. The central bank also expects inflation of 5.2% for the year. If you have a floating-rate loan, a fixed deposit or a monthly grocery bill, that affects you, even if you never read a policy statement.
[Author: add two or three lines of your own here, such as a money mistake you made early or the habit that finally worked. Delete this note before publishing.]
So here’s a practical way to think about money management in 2026, with examples in rupees and no promises of overnight riches.
What personal finance actually covers
Personal finance is how you earn, spend, save, borrow, invest and protect your money. That’s all. The vocabulary around it gets confusing, so a quick split helps.
Money management is the daily part: where this month’s salary goes. Financial planning is the longer map, linking your money to goals like a house, your children’s education and retirement. Wealth management means keeping track of everything you own and owe and arranging it so your assets work toward those goals while the risks stay manageable. You can do all three yourself without a fancy adviser, at least until your situation gets complicated.
Start with household expense management
Everything else depends on knowing where your money goes. Don’t change a thing for the first month. Just track it, using your bank and UPI statements.
Most people are surprised by two things: how much leaks through small, frequent payments, and how many subscriptions they forgot about. Household expense management isn’t about guilt. It’s about replacing guesses with facts.
Take a hypothetical household with ₹70,000 take-home. Rent, groceries, bills and transport add up to ₹38,000. Food delivery, streaming and shopping take another ₹14,000. That leaves ₹18,000, and in practice it often vanishes. The fix for budgeting and saving money is to reverse the order. Decide the savings figure first, say ₹14,000, and have it move out automatically on payday. Spend what’s left, and don’t feel bad about it.
Emergency fund planning comes before investing
I’d put emergency fund planning ahead of any investment, because without a cushion, one bad month forces you to sell investments at the wrong time or borrow at a bad rate.
The usual guidance is three to six months of essential expenses in a place you can reach quickly, like a savings account or a liquid fund. If your essentials are ₹38,000 a month, that’s about ₹1.14 lakh to ₹2.28 lakh. Build it gradually. Even ₹5,000 a month adds up, and people with irregular income should lean to the higher end.
Debt management in a year of rising rates
Debt management matters more after the October hike. If your home loan is linked to the repo rate, your lender may raise your EMI or stretch your tenure, so ask which one and by how much.
Some practical rules. Clear credit card debt first, because it’s the most expensive money you’ll ever borrow. Card interest commonly runs at 36% a year or more, so a ₹1.2 lakh balance can cost roughly ₹3,600 a month in interest alone. Check your own card’s rate. Pay the full bill every month if you can.
Two ways to attack several debts: pay off the highest-interest one first, which saves the most money, or the smallest balance first, which gives quick wins and keeps motivation up. Pick whichever you’ll actually stick to. And as a guideline, keep total EMIs under about 40% of take-home income. If you’re above that, borrowing more is the wrong move.
Financial planning strategies start with goals
Good financial planning strategies begin with a list of financial goals, each with a number and a date. “Save more” isn’t a goal. “₹6 lakh for a car down payment by 2030” is.
Then sort goals by time. Money needed within three years belongs in safe, easy-access places such as deposits or debt funds. Goals five to ten years away can take some equity risk. Goals beyond ten years can take more. Most mistakes come from mixing these up, like putting next year’s school fees into a share that could fall 20%.
Personal finance tips for investing steadily
A few personal finance tips I’d repeat to anyone starting out.
Use a systematic investment plan (SIP) so you invest a fixed amount every month. You’ll buy more units when prices are low and fewer when they’re high, and you’ll never have to guess the right moment. Check the expense ratio of any fund, because fees quietly eat returns over decades. Low-cost index funds are a sensible core for many people. Spread your money across equity and debt. And be sceptical of tips from friends, social media and anyone promising returns.
For long-term wealth creation, time matters more than clever timing. Take a hypothetical ₹12,000 a month invested for 20 years. That’s ₹28.8 lakh of your own money. At an assumed 8% a year it grows to roughly ₹71 lakh, and at an assumed 10%, roughly ₹92 lakh. Those are illustrations, not forecasts. Equity can fall for years, and actual returns vary. But the pattern holds: starting early and staying invested beats searching for the perfect product.
Passive income strategies are more modest than the internet claims
Passive income strategies get oversold. Truly passive money usually needs either capital or effort up front. Interest from deposits, dividends from shares or funds, rent from a property and royalties from creative work are the usual routes.
A hypothetical example: ₹10 lakh in deposits at an assumed 7% pays ₹70,000 a year before tax. That’s useful, not life-changing, and it takes ₹10 lakh to build. Rental income brings tenants, repairs and vacancies. Dividends can be cut. I’d treat passive income as something that grows slowly from savings you’ve already built, not as a shortcut to skip the saving.
Tax-saving investments without the March rush
Every February, people rush into whatever product promises a deduction. That’s backwards. Tax-saving investments such as ELSS funds, PPF, NPS and EPF can be useful, but choose them because they suit your goals, not because it’s the last week of the financial year.
Which tax regime benefits you depends on your deductions. The old regime allows deductions such as Section 80C, capped at ₹1.5 lakh a year at the time of writing, while the new regime has lower slab rates with fewer deductions. Compare both using your actual numbers, and check current rules with the Income Tax Department or a chartered accountant.
Retirement planning is boring and powerful
Retirement planning seems far off at 28, which is exactly why it works then. Start with what you already have: EPF, if your employer offers it. NPS adds a market-linked option. Equity mutual funds can sit alongside.
Estimate what your retirement costs today, then remember inflation will raise it. That’s why part of a retirement portfolio needs some growth assets, not just fixed deposits. Review the plan once a year, and after big life changes like a new child or a job switch.
Financial literacy is the habit that compounds
Financial literacy isn’t jargon. It means knowing what you own, what you owe and what you pay in fees. Read before you sign. Ask what the charges are. Be wary of any promise of guaranteed high returns.
It also helps to talk about money at home. Share account lists, insurance policies and nominee details with a trusted family member, and consider a simple will. Add term insurance if others depend on your income, and health insurance that matches medical costs where you live.
To stay informed, use official sources like the RBI and SEBI alongside reputable media. Malik Times is one outlet that covers money topics, and Malik Times Financial News covers market and rate developments. Readers who want household money topics can browse Malik Times Personal Finance. Cross-check anything that affects your decisions.
Where to start this month
Pick three moves. Track your spending for 30 days. Set up an automatic transfer on payday. Start or top up your emergency fund. Then list your goals and match each to a suitable product. Personal finance rewards steady habits over clever tricks, and nobody gets it perfect the first year.
Quick answers
What is personal finance?
It’s the management of your own money: earning, spending, saving, borrowing, investing and protecting it.
What is the first step in financial planning?
Track your spending for a month, then set goals with amounts and dates.
How much should I keep in an emergency fund?
Three to six months of essential expenses is a common guideline, with more for irregular income.
How does a rate hike affect my loans?
Floating-rate loans can become costlier through a higher EMI or a longer tenure. Ask your lender which applies.
This article is for general information and isn’t investment, tax or legal advice. Rules and rates change, so check official sources, and consider speaking to a SEBI-registered advisor about your situation.